

Buying Property in Kenya 2026: Falling Rates, a Steady Shilling, and the Buyer’s Window You’ve Waited For
Buying property in Kenya 2026: lending rates are easing, the shilling holds near KES 130 and construction is booming. Why this may be your window
For the better part of three years, the honest answer to anyone weighing buying property in Kenya was often “wait”. The shilling was sliding — it touched a historic low of about KES 160 to the dollar in January 2024 — lending rates had spiked, and pricing anything was guesswork. The first half of 2026 presents a different picture, and it is worth laying out plainly why buying property in Kenya 2026 looks different from the two years before it.
Table of Contents
Borrowing is getting cheaper
The Central Bank of Kenya has continued easing. Between July 2025 and June 2026, the Central Bank Rate fell by 10.26% (a relative decline, with the benchmark CBR settling at 8.75%), driving average commercial bank lending rates down by 3.61% into the mid-14% range (14.38% as of June 2026) — a meaningfully more accommodative environment than the 2024 peak, when average lending rates topped 16%.
The mortgage pipeline is being refinanced too. The Kenya Mortgage Refinance Company (KMRC) issued and listed a KES 3.0 billion Sustainability-Linked Note (offering a 12.2% coupon) under its KES 10.5 billion Medium-Term Note Programme. The issuance attracted KES 9.38 billion in bids — a 313% oversubscription — with principal repayments structured across 2027–2034. As long-term local currency wholesale liquidity deepens, primary mortgage lenders (commercial banks and SACCOs) are better positioned to extend longer-tenor, single-digit home loans to retail borrowers.
The shilling has stopped being the story
Since July 2024 the exchange rate has averaged roughly USD 1 = KES 130, holding steady against the dollar, euro and pound — a sharp contrast with the ≈KES 160 low of January 2024. After that turbulence, two years of stability changes buyer behaviour: you can budget a purchase, a construction project or a mortgage without pricing in a currency lurch. Knight Frank expects that stability to persist over the medium term, supported by diaspora inflows and prudent monetary policy.
For diaspora buyers, this is the quiet headline. Converting dollars, pounds or euros into a Nairobi purchase is now a planning exercise rather than a gamble on timing. It is worth noting honestly that remittances have softened — cumulative inflows for the first five months of 2026 were down 1.39% at USD 2.066 billion (about KES 269 billion, indicative at KES 130/USD) — a reminder that the global economy is squeezing everyone. But the stock of diaspora demand for Kenyan property remains one of the market’s foundations.
The economy underneath the housing market
The backdrop is firmer than the global mood suggests. Kenya’s real GDP grew 5.3% in the first quarter of 2026, up from 4.9% a year earlier, even as the World Bank projects full-year growth moderating to 4.4% on global headwinds. More telling for property: construction has swung from contraction (-0.7% in 2024) to a 6.8% rebound in 2025, bank lending to the sector jumped 12.18% to KES 646.5 billion, cement consumption rose 20.3% in 2025, and the value of completed buildings in Nairobi climbed 15.1% to KES 172.4 billion. Builders are building again — and, notably, finishing.
The caveats — in full view
Inflation has crept up. After holding below 5% from July 2024 through the start of 2026, it turned upward in April 2026 and reached 6.7% by June 2026, driven largely by global energy prices amid conflict in the Middle East. It remains within the CBK’s 2.5%–7.5% target band, but if it stays sticky, the pace of rate cuts could slow.
The world economy is fragile. Global growth in 2026 is projected at 2.5% — the weakest since the pandemic — with downside scenarios nearer 1.3%. That reaches Kenya through tourism, exports and remittances.
The election cycle is real. Knight Frank notes many developers are timing project completions for after the 2027 General Election. Sentiment will wobble as 2027 approaches; plan around it rather than panic about it.
Buying Property in Kenya 2026: How to Use the Window
- Get pre-approved now, and rate-shop deliberately — banks, saccos and KMRC-backed lenders are no longer quoting the same numbers.Comparing lenders beyond your primary bank lets you tap into cheaper wholesale or single-digit KMRC funding, saving millions over a long-term mortgage.
- If you hold an older, high-rate loan, ask your bank to reprice it — or refinance. The 2024 peak (lending rates above 16%) is not the 2026 market (mid-14% range).Banks rarely cut running margins automatically, but a formal request can lower your rate or justify moving your balance to a cheaper lender.
- Negotiate the payment plan, not just the price: cash and instalment prices commonly differ by around 5% on developer stock .Offering a larger deposit upfront can unlock cash-tier discounts, while tying remaining instalments to certified milestones protects your cash flow during construction.
- Diaspora buyers: budget in KES while the rate is calm, and note that USD-denominated routes into Kenyan property now exist. Alternative investment structures allow you to hedge currency risks and build exposure without navigating traditional land transfers. You can explore how The Rise of the REITs — Block Advisory insight(REITs) work in our separate guide.
- Buy quality — the supply squeeze in prime residential areas is exactly why well-constructed, professionally managed homes remain the safer store of value. As land scarcity in Nairobi’s established suburbs caps new high-end inventory, premium builds hold their capital far better during market shifts. Take a look at our detailed breakdown on Nairobi’s prime residential supply squeeze to see how inventory constraints are shaping long-term values.
Kenya’s Real Estate Capital Markets in 2026:…
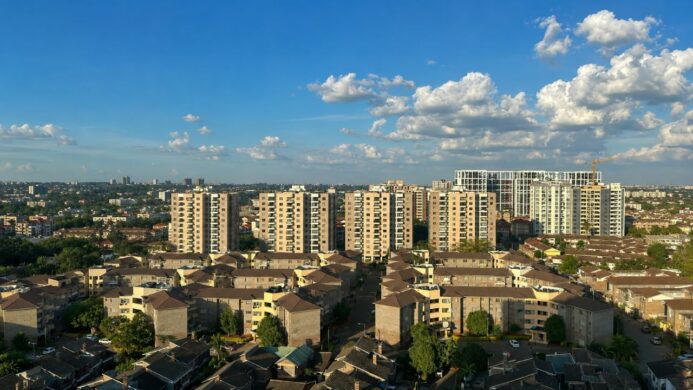
Nairobi’s Prime Residential Squeeze: Prices Up 6.2%…
This is general market information, not financial advice — speak to your bank or a licensed advisor about your own situation.
Ready to run the numbers on a real purchase? Block advises buyers on pricing, financing-ready listings and negotiation across Nairobi’s prime suburbs. Talk to Loyd from Block on 0725 937 686 or [email protected].
Data: Knight Frank, Kenya Market Update — 1st Half 2026; CBK and KNBS as cited therein.